Economic conditions outlook, September 2026
After a spike in pessimism last quarter, executives’ views on economic conditions have tempered. In the latest McKinsey Global Survey on economic sentiment, respondents’ assessments of current conditions have stabilized.1
Even so, the results of the survey, which was in the field from August 31 to September 9, do not suggest renewed optimism. For both the global economy and respondents’ home economies, the shares reporting worsening conditions in the past six months remain larger than those reporting improvements. Furthermore, expectations for the next six months remain divided. Respondents are nearly as likely to expect global economic conditions to worsen as to improve, and their outlooks for their own countries’ economies are similarly split.
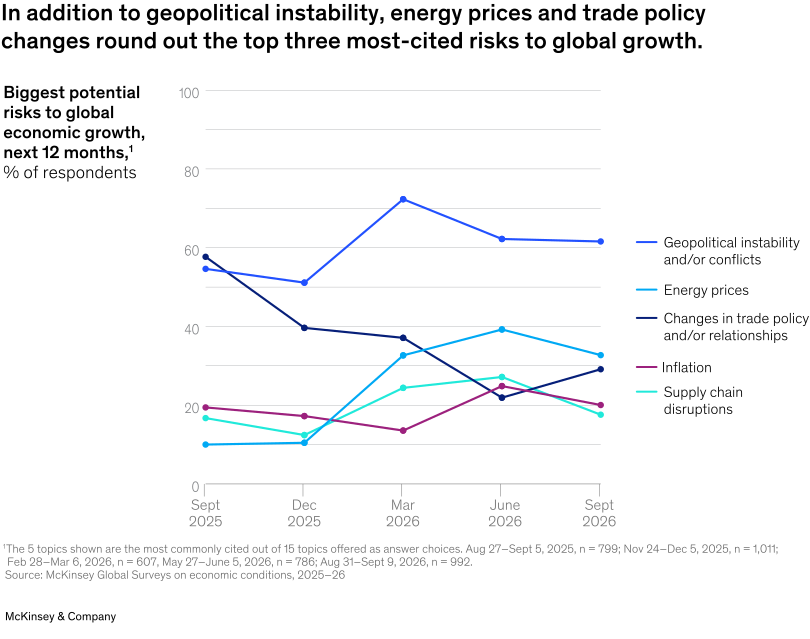
Geopolitical instability and energy prices remain the most commonly perceived economic risks,2 and respondents cite trade policy changes more often than they did in the June survey. In Europe and North America, respondents now also see inflation as a top risk to their countries’ economies. By contrast, the share of respondents citing technological disruption as a short-term economic concern has not increased compared with previous surveys. At the same time, respondents tend to say their own companies are making AI investments a top priority.
Views on current conditions stabilize, but uncertainty lingers
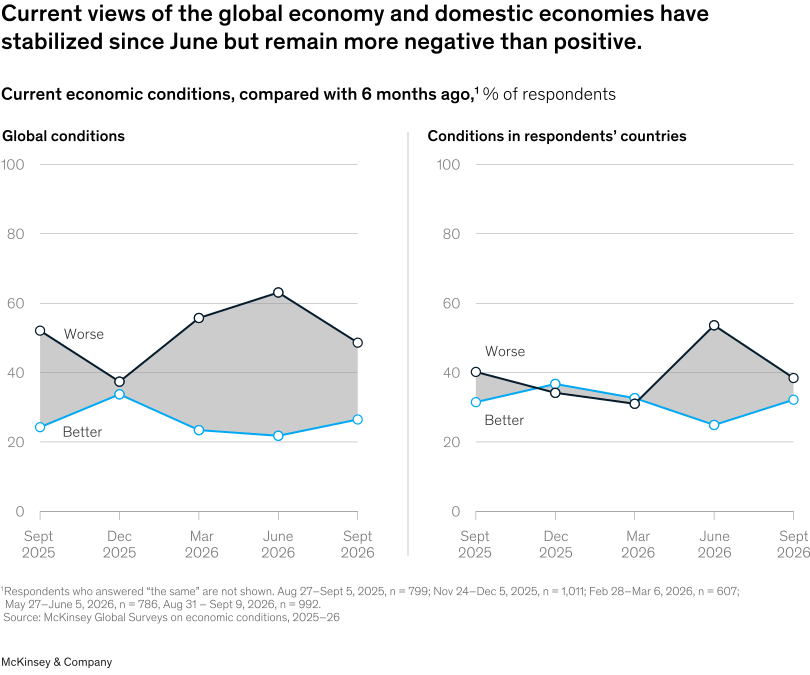
In our June survey, respondents’ views were the most downbeat in recent years: Majorities said the world economy and their own economies had weakened in recent months. Since then, the share of respondents reporting worsening global conditions has fallen, as has the share reporting declining conditions in their own countries (Exhibit 1). The latest reactions to both the global and domestic economies resemble those from one year ago, with larger shares of respondents reporting declining conditions than improving ones.
Given the volatility of views in recent months, we also compared the latest responses with each region’s historical norm, dating back to 2008, to understand whether respondents’ current opinions of their countries’ economies differ from the historical average for their region.3 Unlike in June, when respondents in most regions were much more negative than usual, respondents now primarily report conditions at home that are consistent with their regions’ historical norms (Exhibit 2). However, in North America, respondents continue to report much more negative assessments of their economies than they have historically, while the reverse is true in Greater China.
Since June, views on domestic conditions have largely returned to their historical norms, while Greater China and North America are outliers.
1Historical norms were calculated using data from 68 historical waves dating back to 2008. Responses were indexed to each region’s historical mean, with the historical mean rebased to 100. A figure above 100 indicates sentiment is more positive than the historical average, while one below 100 indicates it is less positive. Feb 28–Mar 6, 2026, n = 607; May 27–June 5, 2026, n = 786; Aug 31–Sept 9, 2026, n = 992.
2Includes Hong Kong and Taiwan.
3Includes Middle East, North Africa, South Asia, and sub-Saharan Africa.

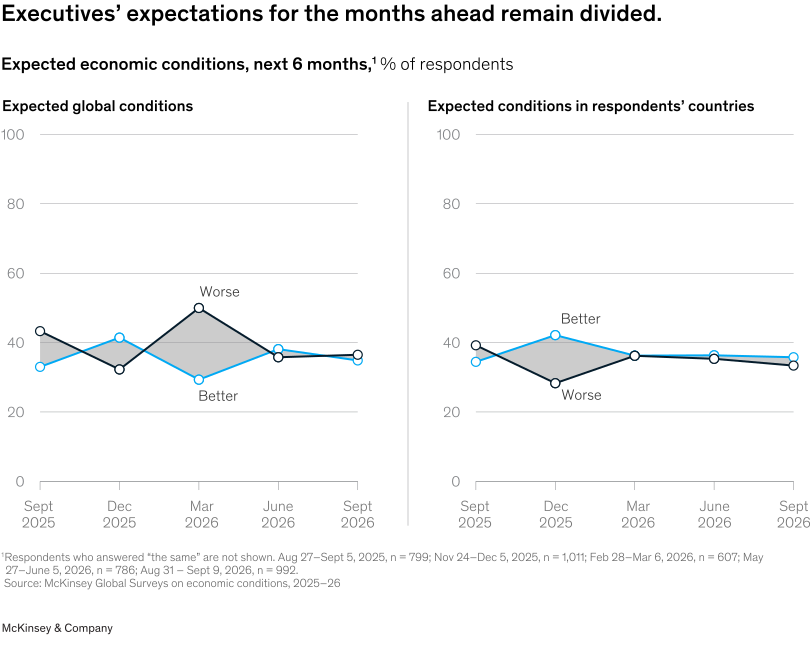
Expectations for the next six months, on the other hand, have changed little since June and remain evenly divided (Exhibit 3). Thirty-five percent of respondents expect the global economy to improve, while 36 percent expect it to worsen. For respondents’ home economies, 36 percent expect conditions to improve, while a similar share (33 percent) expect them to worsen. As was true in June, respondents in Asia–Pacific, Europe, and North America are the most pessimistic, and in the latest survey, less than 25 percent of respondents in each of those regions expect better conditions in the months ahead. Respondents in India, however, are more hopeful than they were last quarter: Half now expect conditions to improve, up from 33 percent.
Geopolitical instability and energy prices remain prominent concerns
While geopolitical instability and conflicts remains the most commonly cited risk to global economic growth over the next year, views on other threats have shifted. The share of respondents citing changes in trade policy or relationships has increased since last quarter and is now nearly as large as the share citing energy prices (Exhibit 4). Meanwhile, respondents’ focus on supply chain disruptions has eased; it is now the fifth-most-cited risk, down from third in June.
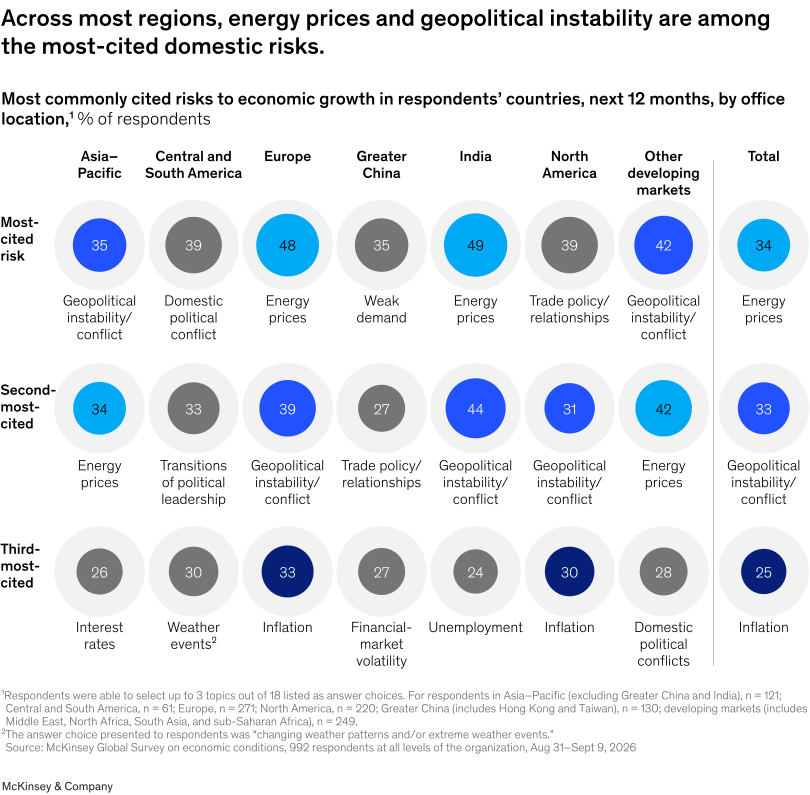
Similarly, the two most-cited risks to respondents’ own countries—energy prices and geopolitical instability and conflicts—are each selected by about one-third of respondents, as was true in June. While geopolitics and related topics are cited most often across all regions, views on inflation meaningfully differ by region (Exhibit 5). In Europe and North America, inflation is increasingly top of mind. In Greater China, respondents were most focused on trade policy changes last quarter; now, the largest share cites weak demand.
Among private sector respondents, weak demand has overtaken geopolitical instability as the most-cited risk to company growth over the next 12 months. The share of respondents citing weak demand rose from 31 percent in June to 36 percent in September, while the share citing geopolitical instability has declined over the past two quarters.
AI is a top business priority—and few see it as a short-term disruption
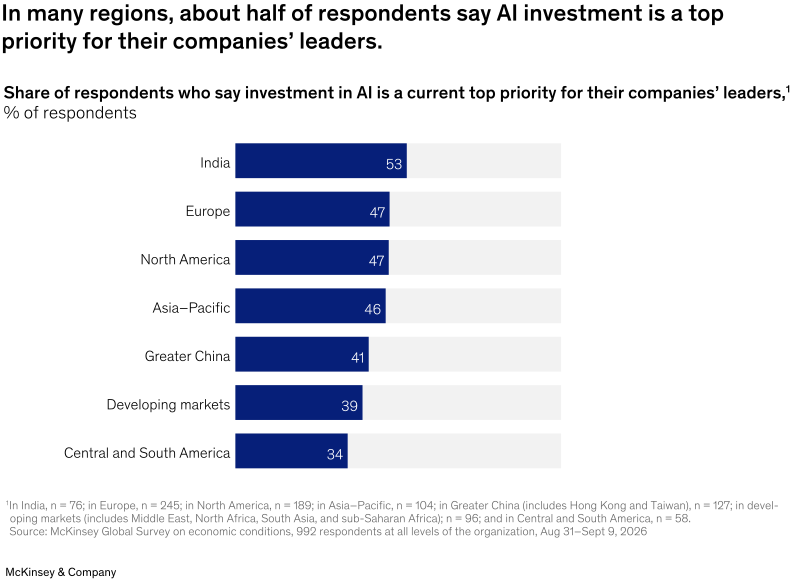
Since early 2016, our survey has tracked where new technologies such as AI rank among executives’ economic concerns and, since 2024, where AI stands as a business priority. Investment in AI has consistently been one of the highest priorities for business leaders over the past two years, and respondents expect the effects of technological disruptions to be felt more in the long term than in the short term. Forty-five percent of respondents now say investment in AI is currently a top priority for their companies’ leaders, up from 40 percent in June. Also, for the third quarter in a row, respondents most often say a shift to new technologies is one of the top growth opportunities for their companies over the next year. The share of respondents who see it as a top opportunity (43 percent) is nearly double the share who see technology as a top risk to their companies’ growth (22 percent).
The focus on technology is especially pronounced in India, Europe, North America, and Asia–Pacific. Respondents in India are the most likely to say AI investment is a high priority for their organizations (Exhibit 6), and they—along with respondents in Greater China—are also particularly likely to view shifts to new technologies as one of the greatest opportunities for their companies over the next 12 months.
When asked about the biggest potential risks to global growth in the year ahead, just 10 percent of respondents cite technological disruptions, roughly the same share as in every quarter since we began asking in March 2024. Similarly, 8 percent identify technological disruptions as a leading risk to growth in their own countries’ economies, which is one-quarter of the share citing the most commonly identified risks: energy prices and geopolitical instability. Looking further ahead, though, technological disruptions did emerge as a top three risk to global growth over the next ten years—behind only geopolitical instability and government policies—when we asked respondents about longer-term risks last quarter.
The latest results indicate that executives’ economic views have steadied, but uncertainty remains. While geopolitical instability, energy prices, and weak demand—as well as inflation in Europe and North America—loom as perceived near-term risks, respondents continue to prioritize AI investment and view technological shifts more as a growth opportunity than an immediate economic threat.
ABOUT THE AUTHOR(S)
Arvind Govindarajan is a partner in McKinsey’s Boston office, where Krzysztof Kwiatkowski is a capabilities and insights expert; Shubham Singhal is a senior partner in the Detroit office; and Jeffrey Condon is a senior knowledge expert in the Atlanta office.
This article was edited by Heather Hanselman, a senior editor in the Atlanta office.
Economic conditions outlook, June 2026
The results from our latest McKinsey Global Survey on economic conditions, conducted May 27 to June 5, 2026, captured executives’ views during a period of heightened economic and geopolitical uncertainty, including disruptions affecting maritime transit through the Strait of Hormuz.4 Against that backdrop, respondents reported a sharp deterioration in economic sentiment from the previous quarter. Nearly two-thirds said conditions in the global economy had worsened over the past six months—the largest share since June 2022—and a majority reported worsening conditions in their own countries’ economies as well.
Even so, respondents were less pessimistic about the global economy’s future than they were in the previous quarter and were about equally likely to expect conditions to improve or decline in the months ahead.
Energy prices emerged as a leading perceived risk to economic growth, alongside geopolitical instability, while larger shares of respondents also cited inflation and supply chain disruptions as concerns. Many reported that their companies were making operational changes in response to the Strait of Hormuz challenges and trade policy shifts. Amid the prevailing uncertainty, companies were more likely to be pursuing conservative rather than growth-oriented investment strategies.
Assessments of the economy hit yearslong lows, while expectations continued to whipsaw
The latest survey showed a significant deterioration in executives’ views of economic conditions, both globally and in their home countries. Sixty-three percent of respondents said global economic conditions have worsened over the past six months (Exhibit 1), the largest share to say so since mid-2022—shortly after the Russian invasion of Ukraine.

Most respondents also said their countries’ economic conditions worsened in the past six months, a period when energy prices hit their highest level since 2022 across major energy commodity classes, and inflation accelerated in both developed and emerging economies. Fifty-four percent of respondents reported worsening economic conditions in their countries, the largest share since respondents reflected on the COVID-19 pandemic’s early days in our September 2020 survey. In nearly every region, respondents were more likely to say economic conditions worsened in the past six months than to report improvement.5 Compared with our March 2026 survey, the sharpest increase in negative sentiment was among respondents in Asia–Pacific and developing markets.
Quarter over quarter, respondents’ expectations for the global economy’s prospects continued to fluctuate meaningfully. The forward-looking picture is more balanced than in March, when respondents were much more willing to expect global economic conditions to decline rather than improve over six months’ time (Exhibit 2). In the latest survey, respondents were about equally likely to expect improving or declining global conditions over the next six months. They were similarly split on their home economies’ prospects: 36 percent expect conditions to improve, and another 35 percent expect they will get worse. (For more on expectations for respondents’ countries, see sidebar, “Short term, attention turned toward the effect of energy market volatility on countries’ economies.”)

Energy prices continued to rise as perceived risks to growth
Geopolitical instability and conflicts remained the most-cited risk to global growth for the third quarter in a row, but the share of respondents who said so decreased since the previous survey (Exhibit 3). Energy prices, which in March trailed behind changes in trade policy and relationships as a perceived risk, were the second-most-cited risk in the latest survey, followed by supply chain disruptions.

The latest results also showed a renewed focus on inflation. Inflation was cited as one of the biggest risks to global growth by the largest share of respondents since June 2024, identified most frequently by respondents in North America.
When asked about risks to their countries’ economies, respondents also saw geopolitical instability and energy prices as the top threats to growth in the next 12 months. The share citing geopolitical instability decreased since March, while the share identifying energy prices grew; in the latest survey, respondents were nearly equally likely to cite each one. Inflation was also cited by a much larger share of respondents than in March.
In almost every region, geopolitical instability and energy prices were two of the most-cited risks (Exhibit 4). North America is an outlier, with the largest share of respondents pointing to inflation and domestic political conflicts.

Companies have made changes in response to recent disruptions—and not just for the short term
Our surveys often track how companies react to external shocks, and the latest survey asked private-sector respondents how their companies responded to the challenges in the Strait of Hormuz. More than half of respondents (57 percent) said their companies had made at least slight changes as a result, while 31 percent reported changes to a moderate or great extent.
Other results suggest that these changes weren’t just short-term. Sixty-one percent of respondents said that, as a result, their companies had begun making long-term changes, such as diversifying supply chains or modifying their country or regional footprint.
When comparing companies’ responses with other past disruptions, we took a look back at the results of our June 2025 survey—several months after new US tariff policies were announced. We saw that respondents in the United States were much more likely to respond quickly to their countries’ trade policy changes than challenges in the Strait of Hormuz, and respondents in Greater China also were more likely to report changes in last year’s survey (Exhibit 5). Respondents in developing markets and in Asia–Pacific were more likely to report meaningful changes in response to challenges in the Strait than to the US trade policy changes.6

We’ve been tracking companies’ operational changes related to US trade policy changes over the past year. Whereas in the previous three quarters, respondents most often said their companies had begun conducting scenario planning, now respondents most often report changes to their supply chains, such as purchasing from new sources.
Companies’ investment approaches leaned more defensive than aggressive
Amid this heightened volatility, many companies were taking a more defensive posture with their investments. The survey asked about companies’ current investment approach for the year ahead and how it compared with their approach in recent years. Respondents were 2.6 times more likely to describe their companies’ current approach as defensive than aggressive (Exhibit 6).7 In every region except for Greater China, the share reporting a defensive stance was larger than the share saying “aggressive.”8

More than one-third of respondents said their companies were being more cautious with their investments in the year ahead than they have been in the past three years—a larger share than those who said their companies were acting more aggressively than usual. Companies that respondents said underperform their industry peers were about twice as likely as those reporting outperformance to say their organizations have a cautious or defensive approach, and also that their companies were investing more defensively than usual.
Taken together, the June results point to an economic outlook defined by geopolitical, energy, inflation, and supply chain pressures. The views on current conditions were notably downbeat. With expectations for the next six months that were much less uniform, executives were preparing for continued volatility.
ABOUT THE AUTHOR(S)
Arvind Govindarajan is a partner in McKinsey’s Boston office, where Krzysztof Kwiatkowski is a capabilities and insights expert; Shubham Singhal is a senior partner in the Detroit office; and Jeffrey Condon is a senior knowledge expert in the Atlanta office.
The authors wish to thank Sven Smit for his contribution to this work.
This article was edited by Heather Hanselman, a senior editor in the Atlanta office.
Economic conditions outlook, March 2026
Executives ended 2025 with more optimism about the economy than they had all year. Those findings changed substantially, however, amid rising geopolitical tensions, according to the first quarterly McKinsey Global Survey on economic conditions of 2026.9
McKinsey Global Surveys have tracked executive sentiment on the economy since 2008. From time to time, we catch major disruptions while the survey is in the field—for example, the early international spread of COVID-19 and the closure of a bank. Such was the case with this latest survey: In the first few days after the survey launched, respondents were as upbeat as they had been in late 2025. But geopolitical tensions escalated in the Middle East on February 28,10 and respondents began to see geopolitical conflict as the top risk to not just the global economy but also to their countries’ economies and their companies’ performance. Optimism about the global economy and domestic economies faltered, though expectations for company growth remained primarily positive.
In this quarter’s update, we treat the responses received after the geopolitical conflict began—which were more pessimistic than those collected in the first few days in the field—as our primary data set.
McKinsey Global Surveys
Conducting research with global executives on the pressing business, economic, and management issues they face.
Geopolitical instability overshadows all other perceived economic risks
Even in the days preceding February 28, respondents most often pointed to geopolitical instability or conflicts as the biggest risk to global economic conditions, which was also true in the December 2025 survey. Seventy-two percent of respondents cite it as one of the biggest global economic risks, up sharply from 51 percent in December (Exhibit 1).11 The share of respondents pointing to energy prices as a risk increased after February 28, and prices appear among the top three most-cited risks for the first time since late 2023. Similarly, the share citing supply chain disruptions—which wasn’t a commonly cited risk in the previous two surveys—doubled after February 28.

The share of respondents citing geopolitical instability as a top risk to their countries’ economies has surged as well and is now the largest since early 2025. It is the most-cited risk in every region.12
Energy prices are among the top five domestic risks for the first time since mid-2023. However, that was true only for the responses coming in on and after February 28. For the first few days the survey was in the field, respondents were about equally likely to cite geopolitical instability and trade policy changes, and energy prices weren’t a top risk (Exhibit 2).

The respondents’ expectations for their companies remain primarily optimistic. Just over half of private sector respondents expect demand for their companies’ products or services to increase in the next six months, similar to last quarter. About six in ten expect profits to grow, consistent with the past two quarters.
However, geopolitical instability is now the most-cited threat to company growth for the first time since March 2025—though before February 28, respondents were about equally likely to cite trade policy changes, geopolitical instability, weak customer demand, and increasing industry competition (Exhibit 3). Geopolitical instability has also become one of the top five topics that respondents say are current priorities for their companies’ leaders, overtaking trade policy concerns.

Confidence in economic conditions ebbs
Overall, a larger share of respondents than last quarter say global conditions declined in the past six months (Exhibit 4).


Expectations for the months ahead also leaned more positive than negative in the first few days in which the survey was in the field, but they ultimately turned much more pessimistic than last quarter’s findings.
Views of specific countries’ current conditions are steadier. Overall, respondents’ assessments of current domestic economic conditions are in line with last quarter’s, with roughly equal shares reporting improvement, worsening conditions, or no change from six months ago.13 Respondents in Europe and North America are the most likely to report worsening economic conditions over the past six months (which was also true throughout 2025), while those in Asia–Pacific, Greater China, and India lean more positive than negative.
Looking ahead to the next six months, respondents share more cautious expectations for their home economies than they did last quarter, when optimism outweighed pessimism. Respondents are now equally likely to expect improvement or deterioration. Thirty-six percent of respondents expect worsening conditions in their countries, up from 28 percent last quarter. In most regions, expectations are similar to those from six months ago, before an optimistic turn in December (Exhibit 5). Respondents in Europe and North America remain the least likely to expect improvement.

Related Articles
Managing geopolitical value at stake to seize opportunities while mitigating risk